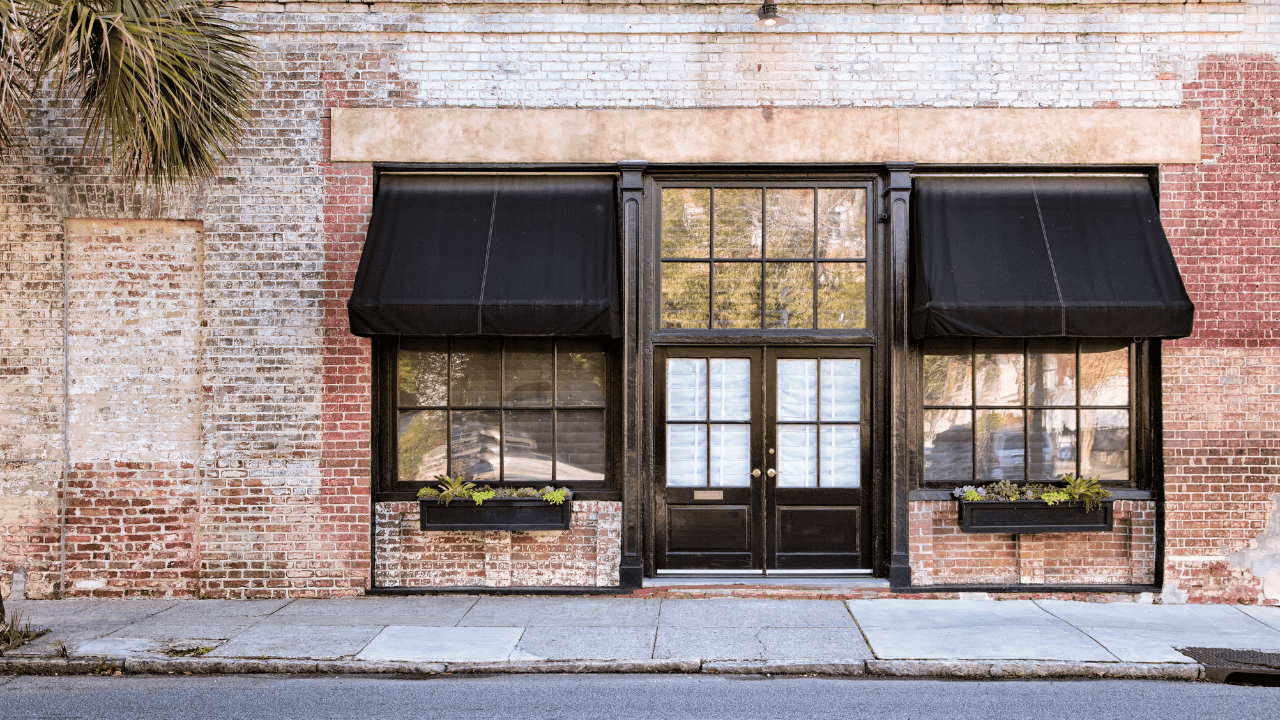
Mixed-use financing exists because a corner store with apartments above it is too commercial for a home mortgage and too small for a shopping-center loan. Most banks either reject it or price it as interest. Ijara Community Development finances that building nationwide: one commercial unit plus up to four residential units.
You do not need a history as a property manager. Ijara does not publish a down payment or a credit floor for this program, so those numbers come on the quote. The term can run up to 30 years. See the provider page and the home financing hub.
Ready to compare halal options?
Who It Is For
This is for the buyer of a live-work building: a halal grocery with two flats upstairs, or a clinic with an apartment in the back. A pure fourplex with no shop belongs on a residential quote. A retail strip with no apartments belongs on a commercial quote.
- One commercial unit
- Up to four residential units in the same building
- You may be a first-time owner of this kind of property
- The building is in any state
Where Mixed-Use Sits
| Building | Better fit |
|---|---|
| House or 1 to 4 unit home | Regular halal home financing |
| Shop plus up to 4 apartments | This mixed-use program |
| 5 to 8 apartments, no shop required | Small multifamily financing |
| Office, warehouse, or retail center | Commercial financing |
| Income hard to document | Pair the building type with a doc program that fits |
The property is held in a single-asset trust and leased to you. The payment is rent on the property, not interest. At the end, title transfers for $1. The trust promises to sell to you. You are not forced to complete the purchase if you walk away under that promise. Mufti Muneer Akhoon chairs the Sharia review.
Get the Right Quote
Guidance Residential and UIF quote homes in the states they serve. They are not the first call for a storefront with apartments. If the issue is paperwork rather than the building type, look at lite-doc financing or no-ratio financing. For a straight rental of one to four units, see halal financing for rental property.
A Quick Example
A building with a ground-floor grocery and three apartments above it fits: one commercial unit, three residential units. A building with two storefronts does not, because the program is one commercial unit. A six-unit apartment building with no shop does not fit here either. Count the units before you apply, and describe them that way in the purchase contract so the file is not underwritten as the wrong product.
You can be new to managing property. That does not mean you should skip a rent roll. If the apartments are vacant, say so. The program does not require a management resume. It also does not promise that vacant units will be ignored when they price the deal. Get the down payment and the credit expectation on the quote, since neither is published.
Top Providers for This Topic


Free to compare · No sign-up required
Read the promise to purchase with a lawyer if this is your first trust-based purchase. The trust has to sell to you. You are not locked into buying if you exit under those terms. Know what walking away actually costs before you rely on that sentence.
Get every halal provider graded (free PDF)
Every US halal provider graded on Shariah integrity, transparency, and value - the full scorecard PDF, plus alerts when grades change
No spam ever. Unsubscribe in one click.
Frequently Asked Questions
Can I get halal financing on a mixed-use building?
Yes. Ijara CDC finances properties with one commercial unit and up to four residential units, nationwide.
Do I need property-management experience?
No. Ijara does not require a property-management history for this program.
How much down payment is required?
Ijara does not publish a down payment or a credit score for mixed-use. Both come on the quote.
Is a fourplex mixed-use?
Not by itself. Mixed-use here means a commercial unit plus homes. A residential fourplex is a different Ijara program.
Do I have to buy the building at the end?
Compare providers in your state
See side-by-side comparisons of Shariah-compliant products, or let our matcher recommend the best options for your situation.
The trust is obligated to sell to you. You are not obligated to buy if you exit under the promise-to-purchase terms. Read that document before you rely on it.